Homeowners in Florida aren't just paying for a roof, windows, or doors to keep out the rain. They are paying for them primarily to stop their property insurance premiums from doubling—or to prevent getting dropped entirely by carriers like Citizens Property Insurance.
With property insurance rates soaring across major metro hubs like Jacksonville, Orlando, Tampa, and South Florida, understanding how a wind-mitigation inspection interacts with your renovation budget is the single most effective way to lower the real cost of homeownership in the Sunshine State. For baseline project estimates, explore our full cost calculator directory.
What is a Florida Wind Mitigation Inspection?
A wind mitigation inspection is a specialized physical evaluation of a home’s structural resilience against hurricane-force winds. Conducted by a licensed building contractor, architect, or home inspector, the inspection documents specific safety features on the state-mandated Uniform Mitigation Verification Inspection Form OIR-B1-1802.
- Average Cost: $75 to $150 (often discounted when bundled with a 4-point inspection)
- Inspection Time: 30 to 45 minutes on-site
- Official Validity: Valid for up to 5 years under most Florida insurance carrier guidelines, provided no structural modifications are made.
Insurance companies are legally required under Florida Statute 627.0629 to provide actuarially reasonable rate discounts and credits for homes equipped with wind-resistant construction features.
The 7 Core Inspection Points Evaluated on Form OIR-B1-1802
When your inspector fills out Form OIR-B1-1802, they grade your home across seven distinct construction categories. Each category unlocks specific insurance credits.
1. Building Code Compliance
- What it checks: Whether your home was built or substantially re-roofed under the strict post-Andrew Florida Building Code (FBC 2001 or later).
- Impact: Homes built to current FBC standards automatically qualify for baseline structural credits.
2. Roof Covering
- What it checks: The approval rating and installation date of your shingles, tiles, or metal roof panels.
- Impact: A Florida Product Approved roof system installed after March 2002 earns higher discounts than older unrated roofs.
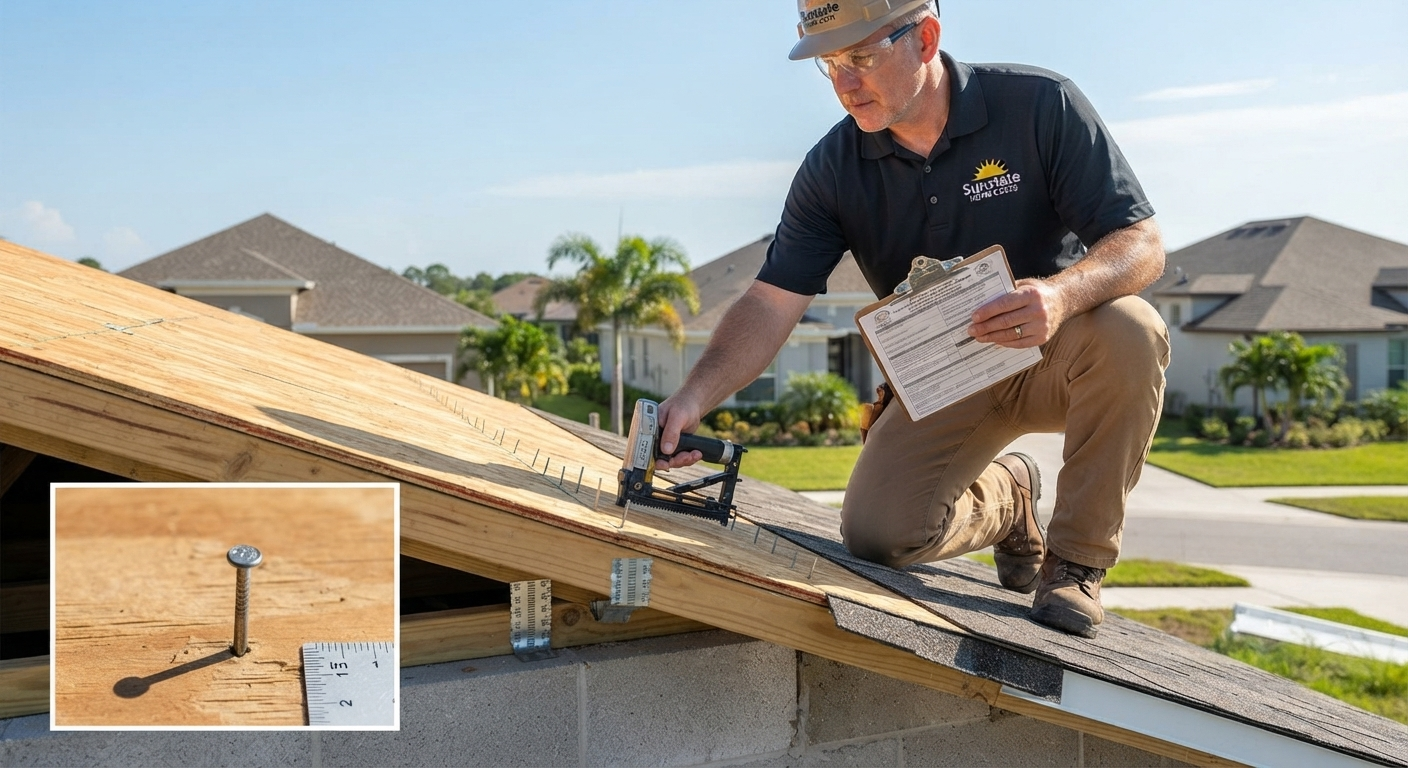
3. Roof Deck Attachment (Nail Size and Spacing)
- What it checks: How the plywood or OSB roof decking is fastened to the structural trusses or rafters. Inspectors check if builders used smooth-shank nails or 8d ring-shank nails spaced at 6-inch intervals.
- Impact: Upgrading to 8d ring-shank nails during a re-roofing project is one of the highest-ROI wind mitigation credits available. Review standard pricing models in our Roof Replacement Cost Guide.
4. Roof-to-Wall Connections
- What it checks: How securely your roof framing is anchored to the concrete block or wood-frame walls. Categories include toe-nails, clips, and single or double wraps.
- Impact: Continuous load-path metal ties and clips offer the highest insurance discounts.
5. Roof Geometry
- What it checks: The shape of your roof.
- Impact: Hip roofs (which slope downward on all four sides) aerodynamic-test significantly better than gable roofs (which feature vertical end walls), yielding substantial insurance savings.
6. Secondary Water Resistance (SWR)
- What it checks: Whether a self-adhering polymer modified bitumen tape or full-deck underlayment was applied directly to the roof joints before shingles or tiles were laid.
- Impact: Prevents water intrusion if your shingles blow off during a major storm.
7. Opening Protection (Windows and Doors)
- What it checks: Whether all exterior glazed openings feature impact-rated glass or tested hurricane shutters.
- Important Note: This is an all-or-nothing category. If even one standard window lacks protection, you receive zero credits for opening protection. Compare upgrade pricing options with our Impact Windows Cost Guide.
Renovation Cost vs. Annual Insurance Savings ROI
National cost calculators ignore Florida's unique financial realities. Below is how renovation investments pair with wind mitigation savings:
| Renovation / Inspection Upgrade | Average Upfront Cost | Estimated Annual Savings | Typical Payback Period |
|---|---|---|---|
| Full Roof Re-Decking (8d Nails & SWR) | $2,500 – $4,500 add-on | $600 – $1,200 / yr | 2 to 4 years |
| Hurricane Roof-to-Wall Clips Retrofit | $1,500 – $3,500 | $400 – $900 / yr | 3 to 5 years |
| Impact Windows & Doors Installation | $12,000 – $28,000 | $1,500 – $3,500 / yr | 7 to 9 years |
| Wind Mitigation Inspection Only | $100 – $150 | $500 – $2,000 (Immediate credit) | Immediate |
Interactive Florida Cost & Insurance Calculators
If your wind mitigation inspection identifies upgrades needed to lower your premiums, use our interactive tools to calculate your expenses and savings:
- Estimate project upgrade pricing with our Florida Roof Replacement Cost Calculator.
- Calculate shutter or glass upgrades using our Florida Impact Windows Cost Calculator.
- Access regional contractor pricing and tools through our complete Cost & Calculations Directory.
Strategic Tips to Maximize Your Inspection Report
- Schedule During Re-Roofing: If you are already replacing your roof, have your contractor take photos of the deck nailing pattern and secondary water barrier before putting down new shingles.
- Verify Credentials: Ensure the inspector performing your OIR-B1-1802 inspection is fully licensed and carries general liability insurance to prevent underwriting rejections.
- Combine With 4-Point Inspections: If your home is over 15 years old, insurance carriers often require a 4-point inspection alongside your wind mitigation report, saving you money on bundled fees. Contractors looking to partner with our directory can learn more on our For Contractors page.
Frequently Asked Questions (FAQ)
How long is a wind mitigation inspection valid in Florida?
A wind mitigation report is officially valid for up to five years from the date of the inspection, provided no structural modifications are made to the property.
Can I perform my own wind mitigation inspection?
No. Under Florida law, Form OIR-B1-1802 must be completed by a certified and licensed inspector, building contractor, professional engineer, or architect.
Do metal roofs lower windstorm insurance more than shingles?
The roofing material itself does not grant a standalone discount, but replacing an old roof with a modern metal roof typically requires a full re-decking and nail upgrade that lowers your premium.
Are wind mitigation discounts mandatory under Florida law?
Yes. Under Florida Statute 627.0629, all admitted insurance companies writing property policies in Florida are legally mandated to offer specific rate discounts when certified features are documented.
Disclaimer: Sunstate Home Costs provides independent home improvement cost data and contractor insights. Pricing and code interpretations vary based on local municipal amendments and engineering requirements. Always verify local building department guidelines and consult licensed contractors before filing insurance claims or undertaking structural modifications.